Historical Context: 2026 Is Outperforming the Average Midterm Year
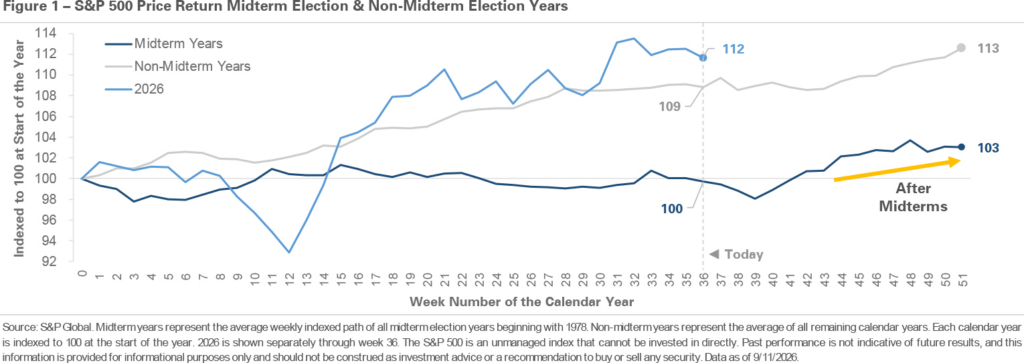
Midterm election years have historically been more volatile than other years, and they’ve historically delivered weaker returns. This year has followed a very different path. The S&P 500 has gained nearly +12% year-to-date. For comparison, the average midterm year is historically flat at the same point, while the average non-midterm year is up nearly +9%. This year has outperformed not only the typical midterm year but also the average non-midterm year. The chart below compares the S&P 500’s year-to-date price return against the average return path of midterm and non-midterm years since 1978, with each year indexed to 100 at the start of the year.
The explanation for the historical midterm pattern is that these years carry an unusual amount of policy uncertainty around future taxes, spending plans, and regulatory changes. Investors generally dislike unresolved questions. Markets have been volatile this year, but the source has been geopolitical and macroeconomic rather than electoral. The S&P 500 fell -5% in Q1 before rebounding more than +20%. Geopolitical tensions have contributed to sharp moves in oil prices, long-term Treasury yields have climbed to multi-decade highs, and uncertainty around the Federal Reserve’s policy has repeatedly shifted the outlook for interest rates. The volatility midterm years are known for has appeared, but the election calendar hasn’t been the cause, and the weak returns haven’t followed either.
The chart also shows markets have historically traded higher once the election passes and attention returns to earnings and economic growth. Those fundamentals have driven the market this year. Strong corporate earnings have helped support the stock market’s valuation. Artificial intelligence investment has fueled spending on data centers, computer chips, software, and power infrastructure, supporting both company profits and broader economic growth. The economy has also continued to expand, supported by steady consumer spending and business investment. None of these drivers depend on an election outcome. Corporate earnings, interest rates, and consumer demand operate on their own timelines.
This year’s divergence from the historical midterm pattern is a useful reminder of the limits of market averages. An investor could have entered 2026 knowing that midterm years have historically produced more volatility and weaker returns. Expecting a difficult market would have been reasonable. The mistake would have been treating that historical average as a return forecast. Historical patterns are useful because they show what markets have tended to do under similar circumstances. They are less useful when the average becomes a prediction for a single year. The takeaway: Use history as context for what might happen along the way, but don’t use it as a forecast of where you’ll end up.
Important Disclosures
Published by Market Desk Research and distributed by QuadCap Wealth Management, LLC.
This client letter is being furnished by QuadCap Wealth Management, LLC (“QuadCap”) on a confidential basis for the exclusive use of clients of QuadCap. and may not be disseminated, communicated, reproduced, redistributed or otherwise disclosed by the recipient to any other person without the prior written consent of QuadCap.
This document does not constitute an offer, solicitation or recommendation to sell or an offer to buy any securities, investment products or investment advisory services. Such an offer may only be made to prospective investors by means of delivery of an investment advisory agreement, subscription agreement and other similar materials that contain a description of the material terms relating to such investment, investment strategy or service. This presentation is being provided for general informational purposes only.
This presentation includes information based on data found in independent industry publications and other sources and is current as of the date of this presentation. Although we believe that the data is reliable, we have not sought, nor have we received, permission from any third-party to include their information in this presentation. Charts, tables and graphs contained in this document are not intended to be used to assist the reader in determining which securities to buy or sell or when to buy or sell securities. Opinions, estimates, and projections constitute the current judgment of QuadCap and are subject to change without notice.
Investing involves risk, including the potential loss of principal. Past performance is not indicative of future results and there can be no assurance that the future performance of any specific investment or investment strategy will be profitable or equal to any corresponding index or benchmark. The information provided is for informational purposes only and does not constitute investment advice, an offer to sell, or a solicitation to buy any security. Investors should carefully consider their investment objectives, risk tolerance, time horizon, and liquidity needs before investing. Please consult a qualified financial advisor before making any investment decisions. The performance information shown herein is based on total returns with dividends reinvested and does not reflect the deduction of advisory and/or other fees normally incurred in the management of a portfolio. The principal risks are: common stock risk, emerging market risk, focused portfolio risk, foreign country risk, foreign currency risk.
Advisory Services are offered through QuadCap, an SEC registered investment advisor. QuadCap only transacts business in states where it is properly registered or is excluded or exempted from registration requirements. SEC registration is not an endorsement of the firm by the Commission and does not mean that QuadCap has attained a specific level of skill or ability.
References to any indices are for informational and general comparative purposes only. There are significant differences between such indices and the investment programs described in this presentation. References to indices do not suggest that the investment programs will, or are likely to, achieve returns, volatility, or other results similar to such indices. The performance data of various indices presented herein was current as of the date of the presentation. Indices are unmanaged, unavailable for direct investment, and do not reflect the deduction of fees and expenses.
The S&P 500 Index or Standard & Poor’s 500 Index is a market-capitalization-weighted index of 500 leading publicly traded companies in the U.S.
The Russell 2000 index measures the performance of approximately 2,000 small-cap US equities.
The MSCI EAFE Index is a stock market index that measures the performance of large- and mid-cap companies across 21 developed markets countries around the world. Canada and the USA are not included.
The MSCI Emerging Markets Index captures large and mid-cap representation across 24 Emerging Markets (EM) countries.
The Nasdaq 100 Index is a stock index of the 100 largest companies by modified market capitalization trading on Nasdaq exchanges.
The Russell 1000 Growth index is an index that tracks large cap, growth stocks. This benchmark is important for investors that might tilt their investments towards large cap growth. Growth stocks, in comparison to value stocks, are considered companies with a more growth potential, and a higher risk profile.
The Russell 1000 Value index is an index that tracks large cap, value stocks. This benchmark is important for investors that might tilt their investments towards large cap value. Value stocks, in comparison to growth stocks, are considered companies with a stable cash flow, and more mature business model.
The Dow Jones Industrial Average, or simply the Dow, is a stock market index that indicates the value of 30 large, publicly owned companies based in the United States, and how they have traded in the stock market during various periods of time. These 30 companies are also included in the S&P 500 Index. The value of the Dow is not a weighted arithmetic mean and does not represent its component companies’ market capitalization, but rather the sum of the price of one share of stock for each component company. The sum is corrected by a factor which changes whenever one of the component stocks has a stock split or stock dividend, so as to generate a consistent value for the index.
The Bloomberg US Aggregate Bond Index is used as a benchmark for investment grade bonds within the United States. This index is important as a benchmark for someone wanting to track their fixed income asset allocation.
The Bloomberg US Corporate Index covers performance for United States corporate bonds. This index serves as an important benchmark for portfolios that include exposure to investment grade corporate bonds.
The Bloomberg US Corporate High Yield Index covers performance for United States high yield corporate bonds. This index serves as an important benchmark for portfolios that include exposure to riskier corporate bonds that might not necessarily be investment grade.
Treasuries, also known as Treasury securities, are debt obligations issued by the United States government. They are used to raise cash needed to fund government operations and help finance the federal deficit. Treasuries are backed by the full faith and credit of the US government, making them one of the safest investments. They are an important instrument in monetary policy, allowing central banks to control the money supply.
The Prime Rate is the interest rate that commercial banks charge their most creditworthy corporate customers. The prime rate is derived from the federal funds rate, usually using fed funds + 3 as the formula.