AI and Geopolitics Continue to Drive Markets
Monthly Market Summary
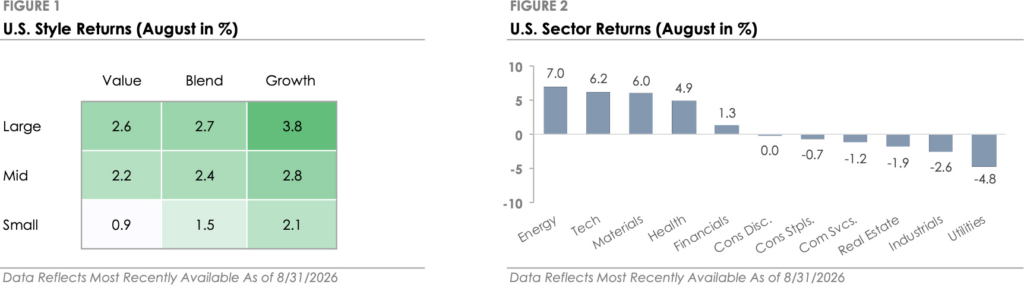
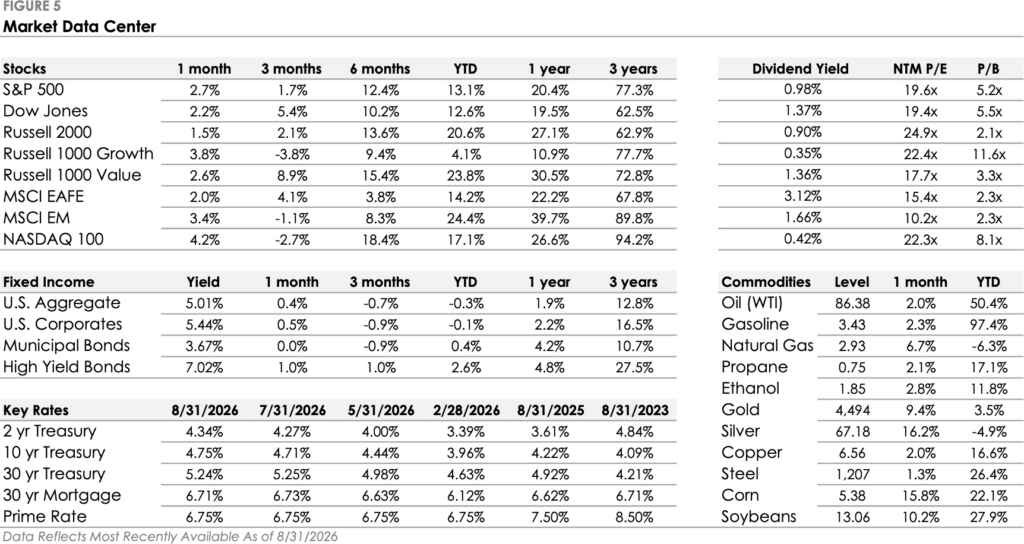
- The S&P 500 Index returned +2.7% in August and set a new high. Five of the eleven S&P 500 sectors traded higher, with four outperforming the broad index. Energy (+7.0%) led all sectors, followed by Technology (+6.2%) as the sector rebounded from a July selloff and Materials (+6.0%) as gold gained nearly +10%. Utilities (-4.8%) led to the downside, followed by Industrials (-2.6%) and Real Estate (-1.9%).
- Bonds traded higher despite Treasury yields rising throughout the month, with the U.S. Bond Aggregate returning +0.4%. Investment-grade corporate bonds modestly outperformed with a +0.5% total return, while high-yield gained +1.0%.
- International stocks traded higher in August. Developed markets gained +2.0% and underperformed the S&P 500, while emerging markets returned +3.4% and outperformed as international tech stocks rebounded alongside U.S. tech stocks.
Stocks Set New Highs Despite Interest Rates Rising Throughout the Month
Equity markets traded higher in August, with strength extending across most broad stock market indexes. The S&P 500, Dow Jones, Russell 2000, and equal-weight S&P 500 all set new all-time highs during the month, and the Nasdaq 100 approached its all-time high from June. The breadth of records was notable because the indexes capture very different parts of the stock market, from mega-cap tech stocks to small-cap stocks and the average S&P 500 company. Market leadership has shifted multiple times this year, alternating between periods of broad participation and concentration. August looked different, with strength spread across a wide range of companies and equity market segments.
The bond market offered a counterpoint to the strength in stocks. Treasury yields experienced broad upward pressure during August, with the 10-year yield climbing above 4.75%, the highest since January 2025, and the 30-year approaching 5.30%, its highest level since 2007. The rise in longer-term yields reflected several concerns, including persistent inflation, elevated government borrowing, and renewed uncertainty around energy prices. Near the end of the month, Fed Chair Kevin Warsh’s Jackson Hole speech signaled that the Fed’s next move could be a rate hike rather than a rate cut, which put further upward pressure on Treasury yields. Despite the rate volatility, corporate credit spreads remained relatively calm and sit near record lows, suggesting investors are more concerned about the path of interest rates than companies’ ability to repay their debt.
Markets Learn to Live with Headline Volatility
Geopolitics have dominated headlines this year, but their impact has changed as the year progresses. Oil prices continue to move when Middle East developments alter the outlook for global energy supply. The difference is that investors appear less willing to treat each new headline as an economic shock. Earlier this year, the start of the conflict and disruption in the Strait of Hormuz caused oil prices to surge and contributed to a broad stock market selloff. Since then, investors have experienced several rounds of escalation and de-escalation. Oil still jumps on new developments, but markets are increasingly waiting for evidence that a headline will affect energy supply, inflation, and economic growth before reacting as dramatically as they did in March.
Artificial intelligence is the second dominant market theme. Investors continue to debate whether the large sums being spent on data centers, computer chips, power generation, and networking equipment will ultimately generate adequate returns, but the companies making those investments continue to move ahead. Nvidia’s earnings report provided another indication that demand for AI infrastructure remains strong, with quarterly revenue more than doubling from a year ago. Spending plans across the industry continue to rise as companies race to add computing capacity and build the infrastructure needed to support AI. There are still questions about the eventual return on the hundreds of billions being spent, but the debate in financial markets has done little to slow the companies making the investments.
This Month in Numbers
Important Disclosures
Published by Market Desk Research and distributed by QuadCap Wealth Management, LLC.
This client letter is being furnished by QuadCap Wealth Management, LLC (“QuadCap”) on a confidential basis for the exclusive use of clients of QuadCap. and may not be disseminated, communicated, reproduced, redistributed or otherwise disclosed by the recipient to any other person without the prior written consent of QuadCap.
This document does not constitute an offer, solicitation or recommendation to sell or an offer to buy any securities, investment products or investment advisory services. Such an offer may only be made to prospective investors by means of delivery of an investment advisory agreement, subscription agreement and other similar materials that contain a description of the material terms relating to such investment, investment strategy or service. This presentation is being provided for general informational purposes only.
This presentation includes information based on data found in independent industry publications and other sources and is current as of the date of this presentation. Although we believe that the data are reliable, we have not sought, nor have we received, permission from any third-party to include their information in this presentation. Charts, tables and graphs contained in this document are not intended to be used to assist the reader in determining which securities to buy or sell or when to buy or sell securities. Opinions, estimates, and projections constitute the current judgment of QuadCap and are subject to change without notice.
References to any indices are for informational and general comparative purposes only. There are significant differences between such indices and the investment programs described in this presentation. References to indices do not suggest that the investment programs will, or are likely to, achieve returns, volatility, or other results similar to such indices. The performance data of various indices presented herein was current as of the date of the presentation.
All investment involves risk. Past performance is not indicative of future results and there can be no assurance that the future performance of any specific investment or investment strategy will be profitable or equal any corresponding index or benchmark. Diversification does not guarantee a profit or protect against loss. The performance information shown herein is based on total returns with dividends reinvested and does not reflect the deduction of advisory and/or other fees normally incurred in the management of a portfolio. Stock performance and fundamental data is based on the following instruments: SPDR S&P 500 ETF (SPY), SPDR Dow Jones ETF (DIA), iShares Russell 2000 ETF (IWM), iShares Russell 1000 Growth ETF (IWF), iShares Russell 1000 Value ETF (IWD), iShares MSCI EAFE ETF (EFA), iShares MSCI Emerging Markets ETF (EEM), Invesco QQQ Trust (QQQ). Fixed Income performance is based on the following instruments: iShares Core U.S. Aggregate Bond ETF (AGG), iShares Investment Grade Corporate ETF (LQD), iShares National Muni Bond ETF (MUB), iShares High Yield Corporate ETF (HYG). Fixed Income yields and key rates are based on the following instruments: Bloomberg US Aggregate, ICE BofA US Corporate, ICE BofA US Municipal Securities, ICE BofA US High Yield, 2 Year US Benchmark Bond, 10 Year US Benchmark Bond, 30 Year US Benchmark Bond, 30 Year US Fixed Mortgage Rate, US Prime Rate. Commodity prices are based on the following instruments: Crude Oil WTI (NYM $/bbl), Gasoline Regular U.S. Gulf Coast ($/gal), Natural Gas (NYM $/mmbtu), Propane (NYM $/gal), Ethanol (CRB $/gallon), Gold (NYM $/ozt), Silver (NYM $/ozt), Copper NYMEX ($/lb), U.S. Midwest Domestic Hot-Rolled Coil Steel (NYM $/st), Corn (CBT $/bu), Soybeans (Chicago $/bu). U.S. Style performance is based on the following instruments: iShares Russell 1000 Value ETF (IWD), SPDR S&P 500 ETF Trust (SPY), iShares Russell 1000 Growth ETF (IWF), iShares Russell Mid-Cap Value ETF (IWS), iShares Russell Midcap ETF (IWR), iShares Russell Mid-Cap Growth ETF (IWP), iShares Russell 2000 Value ETF (IWN), iShares Russell 2000 ETF (IWM), iShares Russell 2000 Growth ETF (IWO). U.S. Sector performance is based on the following instruments: Consumer Discretionary Sector SPDR ETF (XLY), Consumer Staples Sector SPDR ETF (XLP), Energy Sector SPDR ETF (XLE), Financial Sector SPDR ETF (XLF), Health Care Sector SPDR ETF (XLV), Industrial Sector SPDR ETF (XLI), Materials Sector SPDR ETF (XLB), Technology Sector SPDR ETF (XLK), Communication Services Sector SPDR ETF (XLC), Utilities Sector SPDR ETF (XLU), Real Estate Sector SPDR ETF (XLRE).
Advisory Services are offered through QuadCap, an SEC registered investment advisor. QuadCap only transacts business in states where it is properly registered or is excluded or exempted from registration requirements. SEC registration is not an endorsement of the firm by the Commission and does not mean that QuadCap has attained a specific level of skill or ability.
The S&P 500 Index or Standard & Poor’s 500 Index is a market-capitalization-weighted index of 500 leading publicly traded companies in the U.S.
The Russell 2000 index measures the performance of approximately 2,000 small-cap US equities.
The MSCI EAFE Index is a stock market index that measures the performance of large- and mid-cap companies across 21 developed markets countries around the world. Canada and the USA are not included.
The MSCI Emerging Markets Index captures large and mid cap representation across 24 Emerging Markets (EM) countries.
The Nasdaq 100 Index is a stock index of the 100 largest companies by modified market capitalization trading on Nasdaq exchanges.
The Russell 1000 Growth index is an index that tracks large cap, growth stocks. This benchmark is important for investors that might tilt their investments towards large cap growth. Growth stocks, in comparison to value stocks, are considered companies with a more growth potential, and a higher risk profile.
The Russell 1000 Value index is an index that tracks large cap, value stocks. This benchmark is important for investors that might tilt their investments towards large cap value. Value stocks, in comparison to growth stocks, are considered companies with a stable cash flow, and more mature business model.
The Dow Jones Industrial Average, or simply the Dow, is a stock market index that indicates the value of 30 large, publicly owned companies based in the United States, and how they have traded in the stock market during various periods of time. These 30 companies are also included in the S&P 500 Index. The value of the Dow is not a weighted arithmetic mean and does not represent its component companies’ market capitalization, but rather the sum of the price of one share of stock for each component company. The sum is corrected by a factor which changes whenever one of the component stocks has a stock split or stock dividend, so as to generate a consistent value for the index.
The Bloomberg US Aggregate Bond Index is used as a benchmark for investment grade bonds within the United States. This index is important as a benchmark for someone wanting to track their fixed income asset allocation.
The Bloomberg US Corporate Index covers performance for United States corporate bonds. This index serves as an important benchmark for portfolios that include exposure to investment grade corporate bonds.
The Bloomberg US Corporate High Yield Index covers performance for United States high yield corporate bonds. This index serves as an important benchmark for portfolios that include exposure to riskier corporate bonds that might not necessarily be investment grade.
Treasuries, also known as Treasury securities, are debt obligations issued by the United States government. They are used to raise cash needed to fund government operations and help finance the federal deficit. Treasuries are backed by the full faith and credit of the US government, making them one of the safest investments. They are an important instrument in monetary policy, allowing central banks to control the money supply.
The Prime Rate is the interest rate that commercial banks charge their most creditworthy corporate customers. The prime rate is derived from the federal funds rate, usually using fed funds + 3 as the formula.